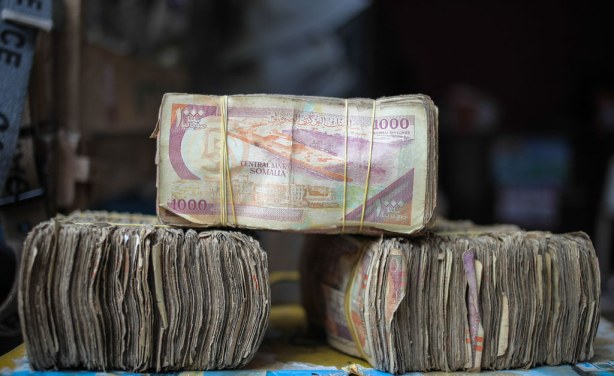
Microfinance: A Catalyst for Economic Development and Poverty Alleviation
Microfinance is a financial service that provides small loans, savings, insurance, and other financial products to people who are typically excluded from traditional banking systems. Its primary target demographic is low-income individuals, small entrepreneurs, and women in developing economies who lack access to formal financial institutions. Microfinance institutions (MFIs) play a crucial role in offering financial inclusion and supporting entrepreneurship, thereby fostering economic development and poverty alleviation. This essay explores the origins, importance, challenges, and impact of microfinance on global development.
Origins and Evolution of Microfinance
The concept of microfinance dates back centuries, but it gained global attention and recognition in the latter half of the 20th century. The modern microfinance movement began with Dr. Muhammad Yunus and the founding of the Grameen Bank in Bangladesh in 1976. Yunus aimed to provide small loans to impoverished people in rural Bangladesh, enabling them to start or expand small businesses. The Grameen Bank’s model focused on group lending and peer accountability, which reduced the risk of default and encouraged borrowers to repay loans on time.
The success of the Grameen Bank sparked interest in microfinance as a tool for poverty alleviation. International organizations, non-governmental organizations (NGOs), and governments began to support the establishment of MFIs in other developing countries. Microfinance has since evolved beyond its roots in small-scale lending to include a range of financial services, including savings, insurance, remittances, and financial literacy training.
Today, microfinance has become a global phenomenon, with millions of borrowers and institutions spread across Asia, Africa, Latin America, and even in parts of developed economies. The industry is supported by a diverse range of players, including NGOs, for-profit MFIs, social enterprises, and large financial institutions that see microfinance as both a social mission and a profitable business.
Importance of Microfinance
The fundamental importance of microfinance lies in its ability to extend financial services to underserved populations, particularly in regions where traditional banking infrastructure is either limited or non-existent. Microfinance has several key benefits:
1. Poverty Alleviation
One of the primary objectives of microfinance is to reduce poverty by empowering individuals to engage in income-generating activities. By providing capital to those who have little or no access to formal banking services, microfinance allows entrepreneurs to start small businesses, invest in education, or improve their housing. The resulting increase in income can lead to better living standards and improved access to health care and education, helping to break the cycle of poverty.
2. Financial Inclusion
Microfinance promotes financial inclusion by integrating marginalized populations into the formal financial system. In many developing countries, traditional banks view low-income individuals as high-risk clients due to their lack of collateral and formal employment. Microfinance institutions, on the other hand, offer financial products tailored to the specific needs and circumstances of these individuals. Financial inclusion not only benefits borrowers but also contributes to the overall stability and growth of the economy by expanding access to capital.
3. Empowerment of Women
Microfinance has played a pivotal role in empowering women, who are often disproportionately excluded from formal financial systems. Many microfinance programs specifically target women, recognizing that they tend to invest their earnings in their families and communities, thus generating broader social benefits. By giving women access to credit and the ability to control financial resources, microfinance promotes gender equality and strengthens their roles within households and society.
4. Support for Small and Medium Enterprises (SMEs)
Microfinance is not limited to individuals; it also serves as a critical source of funding for small and medium enterprises (SMEs). SMEs are often described as the backbone of developing economies, as they create jobs and contribute to economic growth. However, these businesses frequently struggle to secure financing from traditional banks due to a lack of collateral or credit history. Microfinance institutions bridge this gap by offering tailored financial products to support SME growth and innovation.
5. Resilience and Risk Management
Microfinance can help households and small businesses manage risk and build resilience in the face of economic shocks, such as natural disasters, health emergencies, or sudden drops in income. Savings products offered by microfinance institutions enable individuals to set aside funds for emergencies, while microinsurance products can protect against unforeseen risks. As a result, microfinance helps vulnerable populations withstand crises and recover more quickly.
Challenges Facing Microfinance
While microfinance has made significant strides in promoting financial inclusion and poverty reduction, it is not without challenges. Some of the major obstacles facing the microfinance sector include:
1. Over-Indebtedness
One of the most pressing concerns in the microfinance industry is the risk of over-indebtedness among borrowers. With the proliferation of MFIs in some regions, borrowers may take out multiple loans from different institutions, leading to unsustainable levels of debt. In extreme cases, this can result in loan defaults, loss of assets, and deeper poverty. Addressing over-indebtedness requires improved borrower education, better loan monitoring, and responsible lending practices by MFIs.
2. High Interest Rates
Although microfinance aims to serve low-income populations, the interest rates charged by some MFIs can be relatively high compared to traditional banks. These high rates are often necessary to cover the operational costs of delivering small loans to remote and underserved areas. However, they can also place a heavy burden on borrowers, particularly those who struggle to generate sufficient income to repay their loans. Finding ways to reduce interest rates while maintaining the sustainability of MFIs is a key challenge for the sector.
3. Sustainability of MFIs
Sustainability is a critical issue for MFIs, as they must balance their social mission with financial viability. Many MFIs rely on donor funding or government subsidies to cover their operating costs. However, as the microfinance industry matures, there is increasing pressure for MFIs to become self-sufficient and less dependent on external support. Achieving sustainability requires MFIs to adopt sound business practices, improve efficiency, and diversify their revenue streams.
4. Regulatory and Political Risks
Microfinance operates in diverse regulatory environments, and navigating these regulatory frameworks can be challenging for MFIs. In some cases, restrictive regulations may limit the ability of MFIs to offer certain products or services. Conversely, a lack of regulation can lead to the proliferation of unscrupulous lenders and predatory practices. Moreover, political instability in some countries can disrupt the operations of MFIs, affecting both borrowers and lenders.
5. Technological Barriers
While digital financial services have the potential to greatly enhance the reach and efficiency of microfinance, technological barriers can hinder their adoption. In many rural areas, access to the internet, mobile phones, and digital literacy remains limited. Overcoming these barriers is essential for leveraging technology to expand the scope of microfinance services and improve the customer experience.
The Impact of Microfinance on Global Development
Despite the challenges, microfinance has had a profound impact on global development. Numerous studies have shown that access to microfinance can lead to improved household income, better health and education outcomes, and greater resilience to economic shocks.
1. Economic Growth and Job Creation
Microfinance contributes to economic growth by supporting the creation and expansion of small businesses. Entrepreneurs who receive microloans can invest in equipment, inventory, and infrastructure, which in turn leads to job creation and increased productivity. By facilitating the growth of SMEs, microfinance helps to diversify local economies and reduce dependence on subsistence agriculture or informal employment.
2. Reduction in Poverty and Inequality
Microfinance has demonstrated its potential to reduce poverty and inequality, particularly in regions where access to traditional banking services is limited. By targeting the most vulnerable populations, microfinance helps to level the playing field and provide opportunities for upward mobility. In many cases, microfinance has been shown to reduce income inequality by enabling low-income individuals to participate in economic activities that were previously out of reach.
3. Social and Community Benefits
Beyond economic benefits, microfinance has had a positive impact on social outcomes, particularly in terms of gender equality and women’s empowerment. Women who gain access to financial resources through microfinance often experience greater autonomy, improved self-esteem, and increased participation in decision-making processes within their families and communities. Moreover, the group lending model used by many MFIs fosters a sense of solidarity and social cohesion among borrowers.
Conclusion
Microfinance has emerged as a powerful tool for promoting financial inclusion, reducing poverty, and fostering economic development. By providing access to capital and financial services to underserved populations, microfinance empowers individuals and communities to improve their living standards, create jobs, and build resilience against economic shocks. However, the sector faces significant challenges, including the risk of over-indebtedness, high interest rates, sustainability concerns, and regulatory barriers.
As microfinance continues to evolve, addressing these challenges while leveraging the potential of digital technology will be crucial to its future success. Ultimately, microfinance holds the promise of transforming lives and communities, making it a vital component of global efforts to achieve inclusive and sustainable development.
MONK.
A new collection
Learn More →
MONK.
A new collection
Learn More →
MONK.
A new collection
Learn More →
MONK.
A new collection
Learn More →